Casino Payment Methods in Australia 2026: The Rail-by-Rail Reality
 Available in AU
Fund a casino account in this country and you meet a lopsided market. Deposits clear in seconds on rails Australians built inside their own banking system; withdrawals crawl through pending queues built by operators sitting in Curaçao. The rail you pick decides the shape of the whole experience, and most cashier pages hide the trade-offs behind a wall of logos.
This piece maps every payment method available at online casinos serving Australian players in 2026 — from PayID and Osko through Visa and Apple Pay to Skrill, Neosurf, and the crypto family — and puts them on one comparable axis. Not a “top ten casinos” ranking. A method-by-method breakdown that turns the cashier menu into a shortlist matched to what the reader actually needs: fastest cashout, cheapest daily top-up, no bank-statement trace, largest single deposit, thinnest KYC layer.
The offshore reality is baked into every rail below. No Australian state, territory, or federal authority licenses online casinos — the Interactive Gambling Act 2001 blocks it — so every operator that takes an Australian dollar operates from Curaçao, Anjouan, Malta, or another jurisdiction that hands out ticket-of-convenience licences. The player-side legal position is quiet: the IGA targets providers, not punters, and there is no reported prosecution of an individual Australian for using an offshore casino. What punters do face is a payments landscape that keeps shifting as ACMA blocks new domains, banks tighten gambling merchant category codes, and the January 2027 bank-blocking commencement approaches. Every method breakdown below is written into that landscape.
The Australian Payments Landscape at Offshore Casinos
The regulatory shape of AU-facing casino payments is not the usual “which regulator licenses which operator” question. Nothing is licensed. The Interactive Gambling Act 2001 prohibits provision of interactive casino games, in-play sports betting, and online instant-scratch lotteries to persons physically in Australia. State racing and wagering authorities licence sportsbooks. Nobody licences pokies, roulette, blackjack, or live dealer tables online. There is no whitelist to check, no operator-side compliance register to consult, no local ombudsman if a payout goes missing. The market is entirely offshore, and the payment rails an Australian can use to reach it are those the local banking system, the card schemes, and a handful of international wallet and voucher providers agree to service.
The Australian Communications and Media Authority enforces the IGA on the provider side. Since November 2019, ACMA has issued formal blocking directions to Australian internet service providers covering over 1,700 offshore online-gambling services, and 225 operators have voluntarily withdrawn from the Australian market rather than face escalating enforcement. Blocking is DNS/IP-level. It routes an ISP customer trying to open a blocked domain to a redirect page. It does not stop a punter using a VPN, and it does not touch the payment rails themselves. The New Payments Platform continues to settle PayID and Osko transactions to offshore-casino merchant accounts as it settles any other business transaction, because the rail regulator (the Reserve Bank of Australia, oversight of NPP through Australian Payments Plus) does not police the counterparty at the funds-arrival end.
That has begun to change. The Communications Legislation Amendment (Combatting Misuse of Interactive Gambling Services) Act, receiving royal assent in mid-2024, closes the credit-card and cryptocurrency loophole at licensed Australian wagering providers and, more materially for offshore-casino punters, hands banks statutory authority from 1 January 2027 to block payments to ACMA-identified offshore online-gambling services. Between now and that date, every rail below still works as documented. After that date, the mechanics change: the sender’s bank becomes a potential blocking point rather than a neutral pipe, and rails that carry funds through the AU banking system (PayID, Osko, BPAY, card deposits at AU issuers) become the direct target. Crypto rails and prepaid vouchers, whose cash-in step happens on a different rail entirely, sit further from that reach.
AUSTRAC’s role is narrower but relevant. The Anti-Money Laundering and Counter-Terrorism Financing Act 2006 caps prepaid voucher purchases at A$1,000 per person per calendar day, applied across all channels combined. The cap is invisible to casual punters funding A$50–A$200 sessions with a Neosurf voucher, and it becomes a hard ceiling for higher rollers who use vouchers to fund four-figure balances. ASIC oversees card issuers’ conduct on gambling merchant codes, which is why the same Visa card can be blocked at MCC 7995 at one Big Four issuer and cleared at another.
Nothing in this landscape criminalises the reader. That fact needs saying because every second competitor page hedges around it. Playing at an offshore casino from Australia is not an offence under the IGA. The operator is committing an offence by providing the service; the player is not. The trade the punter accepts is the loss of formal recourse: no chargeback rights through an Australian regulator, no AFCA complaint pathway, no BetStop coverage (BetStop applies to licensed AU wagering only). Everything below assumes the reader has weighed that trade and wants to know which rail suits which session.
Does using an offshore casino from Australia break any law?
No. The Interactive Gambling Act 2001 puts the offence on the operator, not on the player, and no prosecution of an Australian punter for using an offshore casino has been reported. What the punter gives up is formal recourse: no ACMA dispute pathway, no BetStop coverage, only card-scheme chargeback rules on the rails.
What happens to my ability to deposit at offshore casinos after the 1 January 2027 bank-blocking changes?
From that date, banks gain statutory authority to block payments to ACMA-identified offshore operators. Rails routed through Australian banks — PayID, Osko, BPAY, AU-issuer cards — become the direct target and may see selective blocking. Crypto exchanges and retail vouchers sit further from that reach; the mix likely shifts toward them.
Every Payment Method at One Comparable Axis
The table below places every rail an Australian punter can use at an offshore casino on the same set of axes. Deposit speed is measured from confirmation at the cashier to the balance being playable. Withdrawal speed is measured end-to-end: the operator’s pending window plus the rail’s own settlement time. Two-way indicates whether the same method carries funds back out. The regulatory-exposure column names the specific pinch point relevant to the rail as things stand in 2026 and as the 2027 bank-blocking commencement approaches.
| Method | Family | Deposit speed | Withdrawal speed (end-to-end) | Min A$ typical | Two-way | Casino-side fee | Regulatory exposure |
|---|---|---|---|---|---|---|---|
| PayID | NPP | Under 60s | 4h–3 days | 10 | Some | Zero | AU banking rail — 2027 blocking target |
| Osko | NPP | Under 60s | 4h–3 days | 10 | Some | Zero | Same as PayID |
| Instant bank transfer | NPP | Under 60s | 4h–3 days | 10 | Some | Zero | Same as PayID |
| POLi | Legacy | Not applicable | Not applicable | Not applicable | Not applicable | Not applicable | Shut down 30 Sept 2023 |
| BPAY | Bank | 1–2 business days | Not supported | 20 | Deposit only | Zero | AU banking rail — 2027 blocking target |
| Visa (debit) | Card | Instant if issuer clears | 3–5 business days | 20 | Some | Zero | Issuer MCC block risk |
| Visa (credit) | Card | Instant if issuer clears | 3–5 business days | 20 | Rare | Zero | Cash-advance flag common |
| Mastercard (debit) | Card | Instant if issuer clears | 3–5 business days | 20 | Some | Zero | Issuer MCC block risk |
| Mastercard (credit) | Card | Instant if issuer clears | 3–5 business days | 20 | Rare | Zero | Cash-advance flag common |
| American Express | Card | Instant if issuer clears | Rare | 20 | Rare | Occasional processor markup | Narrow acceptance |
| Apple Pay | Card wrap | Instant | Underlying card only | 20 | Rare | Zero | Inherits underlying card treatment |
| Google Pay | Card wrap | Instant | Underlying card only | 20 | Rare | Zero | Inherits underlying card treatment |
| PayPal | E-wallet | Near-instant | 1–24h at accepting operators | 10 | Patchy | Zero | PayPal’s own gambling policy |
| Skrill | E-wallet | Near-instant | 15 min–24h | 10 | Baseline | Zero (2.5% wallet-load fee) | Paysafe / FCA |
| Neteller | E-wallet | Near-instant | 15 min–24h | 10 | Baseline | Zero (2.5% wallet-load fee) | Paysafe / FCA |
| ecoPayz / Payz | E-wallet | Near-instant | 15 min–24h | 10 | Baseline | Zero (2.5% wallet-load fee) | PSI-Pay / FCA |
| MiFinity | E-wallet | Near-instant | 1–4h + pending | 15 | Baseline | Zero (2.5% wallet-load fee) | MiFinity / FCA + MFSA |
| Trustly | Open banking | Near-instant | 1–4h + pending | 10 | Some | Zero | Sits on NPP in AU |
| Neosurf | Voucher | Under 10s | Not supported | 10 | Deposit only | Zero | AUSTRAC A$1,000/day cap |
| CashToCode | Voucher | Under 10s | Not supported | 20 | Deposit only | Zero | AUSTRAC A$1,000/day cap |
| Paysafecard | Voucher | Under 10s | Not supported | 20 | Deposit only | Zero | AUSTRAC A$1,000/day cap |
| Pay-by-phone | Carrier billing | Not available in AU | Not applicable | Not applicable | Not applicable | Not applicable | Does not exist here |
| Bitcoin (BTC) | Crypto | 10–30 min | Under 1h + pending | 20 equivalent | Baseline | Zero (network fee A$2–A$8) | Off the AU banking rail |
| Ethereum (ETH) | Crypto | 5–20 min | Under 1h + pending | 20 equivalent | Baseline | Zero (gas variable) | Off the AU banking rail |
| Tether (USDT) | Crypto | 5–15 min | Under 1h + pending | 20 equivalent | Baseline | Zero (network fee ~A$1 on TRC-20) | Off the AU banking rail |
| Litecoin (LTC) | Crypto | 5–10 min | Under 1h + pending | 20 equivalent | Baseline | Zero (fee under A$0.05) | Off the AU banking rail |
| Bitcoin Cash (BCH) | Crypto | 10–20 min | Under 1h + pending | 20 equivalent | Baseline | Zero (fee under A$0.05) | Off the AU banking rail |
| Solana (SOL) | Crypto | Under 1 min | Under 1h + pending | 20 equivalent | Baseline | Zero (fee fractions of a cent) | Off the AU banking rail |
| Dogecoin (DOGE) | Crypto | 10–30 min | Under 1h + pending | 1.20 equivalent | Baseline | Zero (fee under A$0.05) | Off the AU banking rail |
Two facts worth pulling out of that grid before the family breakdowns start. First, the “instant” claim that dominates competitor pages is a deposit-side statement only; on the withdrawal side, the operator’s pending queue lives upstream of every rail. A cashout through PayID may end at the punter’s bank in six seconds, but the operator can hold the request for four hours or four days before it reaches that rail. The rail is fast; the operator is not, and the choice of rail affects the last mile, not the queue. Second, seven rails in that table are deposit-only or effectively so — BPAY, three vouchers, and, in the “rare” column, credit-card variants and Apple / Google Pay when the underlying issuer refuses card refunds. Any punter who deposits on one of those rails needs a second rail lined up for the cashout side before the first spin.
Which payment method is actually fastest for deposits and for withdrawals at an Australian offshore casino?
Deposit-side, Solana wins at sub-second confirmation, with PayID and Osko under a minute; cards, wallets and vouchers all clear “instantly” from the cashier. Withdrawal-side, the operator’s 4-to-72-hour pending queue sits upstream of every rail, so end-to-end speed is the operator first, the rail second — once released, Solana, Litecoin and Bitcoin land within an hour.
PayID, Osko and the NPP-Native Rails
Australia’s New Payments Platform launched in February 2018 and rewrote the deposit side of the offshore-casino experience for locals. Before NPP, an Australian casino deposit meant a card transaction (with the cash-advance friction on credit cards, and issuer blocks on gambling merchant category codes at debit) or a screen-scrape overlay like POLi that piggy-backed on internet banking. After NPP, a punter with a mobile phone and an account at any major AU bank could push AUD to a business receiving account in under sixty seconds, twenty-four hours a day, at zero player-side cost. That rail sits at the centre of every AU-facing offshore cashier that has bothered to build for the local market.
Coverage is near-total. NPP reaches roughly 97% of Australian transaction accounts through the Big Four (Commonwealth Bank, Westpac, ANZ, NAB), Bendigo, ING, Macquarie, and more than sixty smaller institutions. Any bank whose app shows a “PayID,” “Osko,” “Fast Payment,” or “Real Time Payment” option is connected. Sender-side daily limits vary — most retail accounts sit at A$1,000 to A$25,000 per day out of the box, most banks lift the ceiling on request through the app or a call to the branch. Interbank routing is transparent to the sender: the money leaves the sender’s account and lands at the operator’s account regardless of which bank sits on which end.
The catch is not the rail. It is the operator that receives the funds. An offshore casino paying in AUD needs an Australian-domiciled receiving account with a bank willing to onboard a Curaçao-licensed customer, and the number of banks that will is a small, quietly rotating list. When an offshore casino stops accepting PayID, the reason is usually that its acquirer has closed its account rather than that NPP itself has gone anywhere. The 1 January 2027 bank-blocking commencement is the next dated risk on this rail — after that date, the reader’s own bank may selectively block outgoing NPP transfers to ACMA-identified operators, and the practical outcome is impossible to predict rail-by-rail until the first cases surface.
What is the difference between PayID, Osko and instant bank transfer at a casino cashier?
Nothing structural. All three ride the same New Payments Platform rail. PayID is the alias service (mobile, email, ABN) that resolves to a BSB and account; Osko is the consumer brand banks show for real-time NPP; “instant bank transfer” is the neutral cashier label. Same rail, same sub-60-second settlement, same zero player-side fee.
PayID
PayID is the fastest, cheapest, most Australia-native deposit rail on the entire menu. The reader registers a mobile number or email address once with their bank, and from that moment can send AUD to any other PayID identifier — including an offshore casino’s receiving PayID — in under sixty seconds, seven days a week, at zero fee. The bank’s app performs a name lookup against the recipient identifier before the send, which is the point at which the reader confirms the funds are going where they think. Sender-side limits typically start at A$1,000 to A$5,000 per day at consumer accounts and lift to A$25,000 or more when the account holder asks. Withdrawal support at the casino side is common but not universal — where it exists, the reader receives a payout back to the same PayID identifier, again in under sixty seconds once the operator releases the funds. Where it doesn’t, the reader falls back to bank transfer or crypto for the cashout.
The choice comes down to whether the reader wants an AUD-native, bank-native, zero-fee rail with the fastest possible settlement, or whether an alternative rail’s specific advantage — the privacy of a voucher, the two-way symmetry of an e-wallet, the sub-cent fee structure of Solana — outweighs PayID’s speed. For most first-time offshore-casino punters, PayID is the sensible default. It uses money already in the reader’s bank, adds no wallet layer to top up, and clears fast enough that the deposit is playable before the reader has closed the banking app.
Osko
Osko is the consumer-facing brand for real-time transfers on NPP, owned by BPAY Group and adopted by most Australian banks as the label they show inside their app when the reader initiates an instant payment. Structurally, Osko is a rail overlay rather than a distinct payment service — every Osko transfer is an NPP transfer, and every PayID transfer that the bank chooses to label as Osko rides the same wire. At an offshore casino cashier, an “Osko” option and a “PayID” option lead to the same deposit flow: the reader opens the app, initiates a transfer via PayID or BSB/account, the funds land in seconds, the casino credits the balance.
For the reader, the practical difference is zero. The reason to keep the term separate is diagnostic. If a bank app hides Osko behind an “instant payment” toggle rather than a named brand, or if a cashier shows one label and not the other, understanding the label lets the reader map the option to the same rail without hunting through a help page. The 2027 bank-blocking commencement will apply identically to Osko-labelled and PayID-labelled transfers because the underlying rail is the same.
Instant bank transfer
“Instant bank transfer” is the third label many offshore cashiers use for the NPP rail, and it usually means the operator has integrated with a merchant-side aggregator that presents the rail without committing to either the Osko or the PayID brand. The mechanic is identical: NPP settlement, sub-60-second delivery, zero player-side fee. What sits behind the label matters mostly for the fallback case — if the reader’s bank is not NPP-connected (rare, but real for a handful of small credit unions and community banks), the transfer routes through BECS instead, and the deposit turns into an overnight bulk-batch transaction that credits the next business day.
The other reason to keep this label distinct is that some cashiers use “instant bank transfer” to describe an entirely different rail — a Trustly-style open-banking pay-by-bank flow where the reader logs into their bank inside a Trustly frame and authorises a transfer. That flow settles on NPP in AU where the bank supports it, so the end result matches PayID’s speed. But the reader hands PSD2 credentials to a third-party payment initiator rather than initiating from their own banking app, which is a different trust surface. Reading the cashier’s small print before selecting matters here more than at either PayID or Osko.
POLi
POLi is dead in Australia and every “POLi casino” page still ranking in the search results is describing a payment method that no longer exists. POLi Payments Pty Ltd, an Australia Post subsidiary through SecurePay, closed the entire Australian arm of the service on 30 September 2023 with no wind-down period, no migration path, and no successor product. The New Zealand arm continues to operate under Merco Ltd, but for Australian punters, POLi has been off the menu for more than two years by the time this piece publishes.
Three factors killed it. First, POLi ran on a screen-scraping model — the punter handed their internet-banking credentials to a POLi window, POLi logged into the bank on their behalf, and pushed a real-time transfer. That approach was always uneasy with the banks, and by 2023 several of the Big Four had tightened their integration to the point that POLi’s access became unreliable. Second, NPP made POLi obsolete: the punter could push a PayID transfer natively from their own banking app, in the same time, without sharing credentials with anyone. Third, Australia Post decided the AU operation had shrunk below commercial viability. The rail’s disappearance is a fact worth flagging because half the affiliate content on the topic still lists POLi as active — anyone reaching this page from that content deserves the honest answer that the search phrase is a zombie.
BPAY
BPAY sits in the muscle memory of every Australian who has ever paid a council rate or an electricity bill. Log into internet banking, pick “BPAY,” punch in a biller code and a customer reference number, enter the amount, confirm. The rail settles overnight through BECS, so a BPAY deposit at an offshore casino credits the account one to two business days after the send, with weekends and public holidays extending the window. Casino-side acceptance is narrow in 2026 — most operators dropped BPAY when PayID became the fast alternative, and the handful still supporting it treat it as a legacy option for punters whose bank has locked down NPP or who prefer the biller-code paper trail for their own records.
BPAY is deposit-only. There is no BPAY-to-player payout path from an AU-facing offshore casino, because BPAY is a bill-payment scheme that pushes money one way — the biller (in this case, the operator) has no mechanism to send funds back to the sender’s account through the same rail. Any BPAY deposit at a casino needs a second rail lined up for the cashout, usually PayID at the same operator, sometimes crypto, occasionally bank transfer. As the 1 January 2027 bank-blocking commencement approaches, BPAY sits in the same regulatory line of sight as PayID — it runs through Australian banks paying an Australian biller, and it is exactly the kind of transaction the amended framework empowers banks to block.
Cards, Apple Pay and Google Pay
Every Australian consumer bank issues Visa or Mastercard debit and credit cards, and both schemes carry the broadest acceptance across AU-facing offshore casino cashiers. American Express is narrower. Apple Pay and Google Pay are wrappers over the same cards, adding a tokenised device layer that does not change the underlying issuer treatment. Card rails are the default for punters who have not opened an e-wallet or bought a voucher, and they are also the rail with the most hidden cost — the cash-advance flag on credit cards, the gambling merchant category code block at the issuer level, and the limited withdrawal-symmetry that forces most punters onto a second rail for the cashout.
The MCC block is worth understanding because it is not consistent across issuers. Australian banks treat merchant category code 7995 (gambling) at issuer discretion. Some of the Big Four block MCC 7995 outright on credit cards while allowing it on debit; others permit both; a handful of neo-banks and challenger banks (Up Bank, ING) apply the block symmetrically. When a card deposit at an offshore casino declines, the reader is usually looking at an issuer-side MCC block rather than a casino-side rejection, and the cashier’s error message is generic (“payment declined”) because the operator has no visibility into the issuer’s reason code. Switching to a debit card from a different issuer, or to a wallet that fronts the same card, sometimes clears the block; sometimes it does not.
Are credit-card deposits at offshore casinos coded as a cash advance by Australian banks?
Often. Australian issuers frequently treat gambling MCC 7995 on credit as quasi-cash, triggering cash-advance interest from day one at the higher cash-advance rate, disqualifying the interest-free period and sometimes adding a per-transaction fee. Debit cards escape the cash-advance concept because the money is yours, but MCC blocks apply to debit too, at issuer discretion.
Visa
Visa is the broadest card option at AU-facing offshore casinos. Almost every operator that accepts cards accepts Visa; almost every Australian consumer bank issues Visa debit and Visa credit. Deposits process instantly when the issuer clears the transaction, and the cashier credits the balance in the same second the authorisation completes. The trouble sits on two sides. On the credit side, Australian issuers commonly treat gambling merchant category code 7995 as quasi-cash, coding the deposit as a cash advance from day one at the higher cash-advance interest rate, sometimes with a per-transaction fee attached. On the debit side, the issuer’s MCC-block policy determines whether the transaction clears at all — the Big Four apply different policies, neo-banks apply more consistent ones, and the punter needs to test with a small deposit before assuming their card will work.
Withdrawal symmetry is limited. Most AU-facing offshore casinos offer card-to-source refunds for Visa deposits up to the deposited amount, with excess winnings routed to a different rail (bank transfer, crypto, or e-wallet). Some operators do not support card refunds at all, in which case the entire cashout runs through a second rail. Where card refunds do work, settlement to the punter’s card statement usually takes three to five business days. That timeline aligns with card-scheme processing rather than the operator’s pending queue, so the “up to seven business days” figure some cashiers quote is a padding margin, not a hard limit.
Mastercard
Mastercard’s landscape at AU-facing offshore casinos is virtually identical to Visa’s. Every operator that accepts one accepts the other; every Australian issuer that issues one issues the other. Deposits process instantly when the issuer clears; the cash-advance treatment on credit applies with the same MCC 7995 logic; the withdrawal-symmetry pattern is the same three-to-five business day card refund where the operator supports it. The choice between Visa and Mastercard at the cashier is dictated by which card the reader has in hand, not by any structural difference in how the two schemes handle offshore-casino traffic.
There is one narrow diagnostic difference. When an issuer blocks a card at the gambling MCC, the block occasionally applies to one scheme and not the other at the same issuer — usually as a temporary anomaly during a policy rollout rather than a permanent state — so if a Visa deposit at an operator declines and the same operator accepts Mastercard, trying the Mastercard is sometimes worth a small test. Beyond that, the two rails are interchangeable.
American Express
Amex is a narrow card option at AU-facing offshore casinos. Its higher merchant fees and stricter contractual controls make it unattractive to Curaçao-tier operators, and the number of AU-facing sites that process Amex sits in the low single digits across the archive of coverage informing this piece. For the reader with an Amex card in hand, checking each operator’s cashier before assuming Amex will work is the practical starting point — the logo is often absent even when Visa and Mastercard both appear.
Where Amex is accepted, the reader picks up two side benefits. First, Amex proprietary AU cards (David Jones, Qantas Ultimate, Membership Rewards Explorer, Platinum Charge and Reserve) accrue rewards points on the deposit at the same rate they accrue on any other retail transaction — a subtle but real value pickup if the cardholder chases points. Second, Amex’s own dispute-resolution process is stronger than Visa’s or Mastercard’s at the scheme level, which is a marginal comfort on an offshore transaction where the punter has no local ombudsman to appeal to. Both benefits are eclipsed by the acceptance-count problem: Amex is not the rail to build a session around, but it is worth using when it happens to be available.
Apple Pay
Apple Pay is a tokenisation wrapper over an underlying Visa, Mastercard, or Amex card, biometric-authenticated on the device. The casino cashier sees the card scheme, not “Apple Pay” — the payment lands as a Visa or Mastercard transaction with the appropriate merchant category code, and every issuer-side rule that applies to the underlying card applies here. Deposit speed is instant when the underlying card would clear; the token model adds no friction. The advantage sits at the user-experience layer: no card number typed into a casino cashier, no CVV, no separate confirmation code — just Face ID or Touch ID and a tap.
Withdrawal-symmetry inherits the underlying card’s behaviour. If the operator supports card refunds and the underlying card is a debit card, a cashout routes back to the token, which routes to the underlying card, which settles into the punter’s bank account in three to five business days. If the underlying card is credit and the operator supports card refunds, the refund credits the credit-card statement in the same window, but many issuers do not treat card refunds identically to purchases, so the timing can drift. For most sessions, Apple Pay is a friction-free deposit rail with the same limitations as its underlying card, not a distinct rail with its own withdrawal profile.
Google Pay
Google Pay is the Android equivalent of Apple Pay: the same tokenisation model, the same card-scheme wrap, the same issuer-side treatment of the underlying card. Deposit speed is instant when the underlying card clears. Withdrawal-symmetry inherits the underlying card’s behaviour in the same way Apple Pay’s does. The choice between the two is dictated by the reader’s device, not by any structural difference in how the two wallet products handle offshore-casino traffic. On both, the practical usefulness sits in the deposit convenience — no card details typed into a cashier form — and the practical limitation sits in the withdrawal side, where the token layer does not change the fact that the underlying card is the actual rail.
E-Wallets — Skrill, Neteller, ecoPayz / Payz, MiFinity, PayPal, Trustly
E-wallets are the rail most punters end up on once they have opened their second or third offshore-casino account. The pattern is familiar: the reader starts with PayID or a card, hits a specific operator that requires an e-wallet for one bonus or one cashier lane, sets up a Skrill or Neteller account, and quickly finds the wallet more convenient than switching rails per operator. Every e-wallet on this menu sits in the same speed tier — deposits are instant, withdrawals arrive at the wallet within 15 minutes to 24 hours of operator approval — and every wallet extracts a similar fee at the load step, usually around 2.5% of any Australian debit-card top-up. The differences among the wallets are acceptance count, brand trust, and the specific quirk each one adds (PayPal’s own gambling policy, MiFinity’s dual FCA/MFSA licensing, ecoPayz’s tiered upgrade path).
The 2.5% funding fee is the structural cost most cashier pages skip. The wallet-to-casino leg is free; the punter-to-wallet leg is where the wallet’s card processor collects its margin, and for Australian users that margin is a flat 2.5% because AU debit cards do not qualify for the wallet’s EEA card rate. FX margin adds another layer when the casino operates in a non-AUD currency — Skrill and Neteller apply roughly 2.99% on standard pairs (AUD/EUR, AUD/USD), MiFinity uses a similar spread. When the operator’s cashier runs in AUD natively, the FX layer disappears; when it runs in euros or US dollars and the wallet holds AUD, the load fee and the FX margin compound.
Which e-wallet has the widest AU-facing casino acceptance?
Skrill and Neteller share the widest acceptance — both because they are the longest-established iGaming wallets and because they share a parent (Paysafe Group), so operators integrating one usually integrate the other. Both appear at more than fifty AU-facing operators. ecoPayz / Payz sits behind them, then MiFinity, then Trustly, with PayPal narrowest.
PayPal
PayPal is the most trusted brand in the Australian consumer wallet and the least broadly accepted e-wallet at AU-facing offshore casinos. The reason sits in PayPal’s own merchant-approval process: PayPal restricts gambling transactions in jurisdictions where local licensing is prohibited, and Australia — where no online casino licence exists — falls into that category. Offshore operators wanting PayPal have to clear a merchant-vetting process that most Curaçao-tier operators cannot or do not bother to complete. The result is a small AU-facing PayPal footprint, roughly eight verified operators in the source archive that informs this piece.
Where PayPal is accepted, the punter picks up a real advantage. The KYC layer is already done at the wallet — PayPal knows who the reader is — and the deposit flow is a single “Confirm with PayPal” tap that clears near-instantly. Withdrawal support is patchier: some operators accept PayPal deposits but route cashouts through bank transfer or crypto, others support two-way flow. Where two-way flow works, PayPal cashouts arrive at the wallet within an hour of operator approval. Where it doesn’t, the reader needs a second rail lined up for the cashout side.
Skrill
Skrill is the reference iGaming wallet in this market. Owned by Paysafe Financial Services in the UK and authorised by the Financial Conduct Authority, Skrill has been in the online-gambling space long enough that its acceptance is baseline at every AU-facing offshore operator with any serious e-wallet integration — more than fifty operators in the source archive support it. Deposits are near-instant. Withdrawals to Skrill arrive at the wallet within 15 minutes to 24 hours of operator approval, depending on the operator’s pending window and its withdrawal-processing tier. Two-way support is standard rather than an exception.
The cost sits at the load step. An Australian debit-card top-up to a Skrill wallet carries a 2.5% funding fee, and an FX margin around 2.99% applies if the punter loads AUD and the casino cashier operates in euros or US dollars. Card-load fees stack on card-load fees if the reader tops up multiple times per session. Skrill’s own withdrawal from wallet to bank costs a small fee per transaction (typically A$2–A$5 equivalent). For a punter who deposits once, wins, and withdraws to bank, the round-trip cost usually sits between three and six percent of the deposited amount, most of which shows up at the initial wallet load rather than at the casino side.
Neteller
Neteller is Skrill’s older sibling under the Paysafe umbrella and shares almost every mechanic — same 2.5% AU card-load fee, same 15-minute to 24-hour wallet-side withdrawal window, same near-universal acceptance across AU-facing operators that carry Skrill. Historical footprint runs slightly deeper: Neteller predates Skrill and holds legacy accounts at some higher-roller operators where Skrill acceptance is less consistent. In practice, the punter who has one wallet already has the other by default, because Paysafe pushes cross-sign-up through both brands, and operators list the two together on every cashier page.
The narrow reason to pick Neteller over Skrill at any given operator sits in the promotional and VIP layer. Some operators run wallet-specific bonuses (Neteller-only reload matches, Skrill-only free-spin drops) that vary week to week, and the punter can occasionally pick up a marginal edge by watching which wallet the operator is currently promoting. Outside those niche pickups, Neteller and Skrill are interchangeable, and the choice is dictated by which brand the reader already trusts.
ecoPayz / Payz
ecoPayz rebranded to Payz in mid-2023, which cost a chunk of brand recognition and triggered a short-term dip in AU-facing casino acceptance as operators updated their cashier logos and merchant contracts. The rebrand is now bedded down. The wallet is owned by PSI-Pay Ltd, a UK-authorised e-money institution regulated by the Financial Conduct Authority, and its structural quirk is a tiered account model (Classic / Silver / Gold / Platinum / VIP) where higher tiers unlock larger limits and lower fees. Basic Classic tier opens with a light KYC step; progression to higher tiers requires stepped identity verification.
Deposit and withdrawal mechanics land in the same tier as Skrill and Neteller — instant deposits, wallet-side withdrawals inside 15 minutes to 24 hours of operator approval, 2.5% AU card-load fee at the wallet-funding step. AU-facing acceptance count sits behind Skrill / Neteller but ahead of MiFinity and Trustly. For a high-volume punter, the tiered model is worth exploring, because the ceiling lift and the fee-schedule reduction at Gold or Platinum meaningfully outperform the flat rate at Skrill or Neteller. For casual sessions, ecoPayz / Payz is a straight substitute for either Paysafe wallet with no advantage or disadvantage worth flagging.
MiFinity
MiFinity is the newer AU-facing e-wallet, backed by MiFinity Ltd of Ireland and dual-licensed by the Financial Conduct Authority in the UK and the Malta Gaming Authority. Dual licensing is real depth on the regulatory side — few iGaming wallets carry both — and the wallet has been growing its AU-facing operator count steadily through 2024 and 2025, currently sitting around 15 or more operators in the source archive. Deposits at the casino side are near-instant, and withdrawals from the operator’s cashier to the MiFinity wallet arrive in one to four hours after operator approval, with the standard 12-to-72-hour pending window sitting upstream.
MiFinity’s structural cost matches the rest of the wallet family. Australian debit cards carry a 2.5% funding fee at the wallet-load step, because Australian cards are non-EEA and MiFinity’s cheaper EEA-card rate (1.8%) does not apply. FX margin sits at up to 2.99% on standard pairs and up to 3.99% on exotic pairs — AUD is a standard pair, so the reader pays 2.99% when the casino cashier operates in a currency other than AUD. SEPA transfers to the wallet are free, but SEPA is a European rail Australian banks do not offer, so the free-transfer option is out of reach in practice. For a punter comparing MiFinity to Skrill or Neteller at a specific operator, the choice usually comes down to which wallet the operator has integrated more cleanly rather than a fee-schedule advantage.
Trustly
Trustly is not a wallet in the Skrill / Neteller sense. It is an open-banking pay-by-bank service run by Trustly Group AB in Sweden and licensed under PSD2 as a payment initiation service provider. The flow at an offshore cashier is different: the reader picks Trustly, a Trustly frame opens inside the cashier, the reader logs into their bank inside the frame, authorises a direct account-to-account transfer, and the funds land at the operator’s account without ever passing through a Trustly-held wallet. Speed on the AU side inherits from NPP where the bank supports it, so the settlement tier is the same as PayID.
The trust surface is where the difference matters. The reader hands PSD2 credentials to Trustly for the duration of the session rather than initiating from their own banking app. Trustly’s regulatory footing is solid (PSD2, EU-supervised), and the credential exchange happens inside a Trustly-hosted frame rather than being screen-scraped, so the security posture is materially different from POLi’s old model. AU acceptance sits below the classic e-wallets — a handful of AU-facing operators in the source archive — but it is present, and for a reader who prefers not to top up a wallet before depositing, Trustly is the closest thing to PayID with a different UX layer.
Prepaid Vouchers — Neosurf, CashToCode, Paysafecard
Vouchers exist to remove the bank from the deposit path. Buy a voucher at retail or online, receive a PIN, redeem the PIN at the casino cashier, and the deposit lands in seconds with no line on the reader’s bank statement, no card decline, no gambling merchant-code drama. The privacy pitch is real and the mechanics are straightforward. What every voucher shares — Neosurf, CashToCode, Paysafecard — is that they are deposit-only bearer instruments. Whoever holds the PIN controls the balance, there is no account layer, and there is no return mechanism. Every voucher deposit needs a second rail lined up for the cashout, because the voucher itself cannot receive money back.
The AUSTRAC cap is the other rule to know before treating vouchers as a large-deposit option. Prepaid voucher purchases are capped at A$1,000 per person per calendar day across all channels combined. The cap is invisible to a punter buying a A$50 Neosurf on the way home from work, and it becomes a hard ceiling for anyone trying to fund a four-figure balance. Buying A$1,000 in vouchers today and A$1,000 tomorrow to reach A$2,000 in casino balance is legal; buying A$2,000 in vouchers in one day at any combination of retail and online outlets is not. The retailer’s till and the online seller’s system both enforce it.
Can I withdraw to a Neosurf voucher after depositing with one?
No. Neosurf is a deposit-only bearer instrument with no account layer and no return mechanism, so the operator cannot mint and deliver a fresh PIN. Every Neosurf deposit needs a second rail lined up for cashout — crypto for speed, PayID for AUD-native, bank transfer as fallback.
Neosurf
Neosurf is the reference voucher in the AU-facing offshore-casino market. The rail is French (Neosurf Cards Ltd) and the AU retail footprint spans more than 1,000 outlets: BP, Caltex, Shell, 7-Eleven, Australia Post counters, IGA, and select Woolworths stores stock A$10, A$20, A$50, and A$100 physical vouchers. Online, the denominations extend to A$500 through the Neosurf website, Recharge.com, MyGiftCardSupply, and Dundle. The reader walks in, hands over cash or EFTPOS at the till, walks out with a receipt bearing a 10-digit PIN, and at the casino cashier enters the PIN and the amount to redeem. The deposit lands in under ten seconds.
Deposits are almost always fee-free on the casino side. The retailer typically charges face value with no purchase margin, though online resellers occasionally add a 1–3% service fee, and vouchers expire twelve months from the purchase date. Partial redemption is supported — a A$50 voucher can push A$30 into the casino balance, leaving A$20 on the same PIN for later use at the same or a different merchant. The AUSTRAC A$1,000/day cap sits above all this as the structural ceiling. On the casino side, minimum deposits usually sit at A$10 to A$20; some operators lift the floor to A$20 or A$30 to align the deposit minimum with the withdrawal floor. Neosurf’s withdrawal-side reality — that no cashout can ever route back to a voucher — is the single most important fact to internalise before funding a session this way.
CashToCode
CashToCode is the second voucher in the AU offshore market, using a 20-digit PIN delivered by email after online purchase. AU retail footprint is narrower than Neosurf’s — CashToCode partners with a smaller set of retail outlets, and the practical purchase path for most AU punters runs through the CashToCode website or a partner reseller rather than the servo counter. The rail’s mechanics are otherwise identical to Neosurf: deposit-only, near-instant redemption at the casino cashier, no casino-side fee, subject to the AUSTRAC A$1,000/day cap.
The reason a reader picks CashToCode over Neosurf usually comes down to operator availability rather than any structural advantage. CashToCode sits at roughly eight AU-facing operators in the source archive, so the punter’s operator either accepts one or the other — occasionally both, more often just one. For a reader who wants voucher privacy and finds their preferred operator on CashToCode, the rail delivers exactly what Neosurf does. For a reader whose operator is Neosurf-only, CashToCode adds nothing.
Paysafecard
Paysafecard is the international voucher network in the Paysafe Group family, and its AU-facing footprint has been shrinking as operators consolidate on Neosurf. The rail uses a 16-digit PIN and behaves at the cashier exactly the way Neosurf and CashToCode do: deposit-only, near-instant redemption, no casino-side fee, subject to the AUSTRAC A$1,000/day cap. The wider Paysafe brand recognition (from the Skrill / Neteller side of the business) does not translate into deeper AU-facing casino acceptance for the voucher itself, which sits at a handful of operators in the source archive.
Where Paysafecard remains available, it functions identically to Neosurf. The choice is dictated by operator support rather than any inherent advantage of one voucher over another. For readers who arrive at an offshore cashier and see only Paysafecard on the voucher menu, the rail is a working option; for readers with the choice between Paysafecard and Neosurf at the same operator, Neosurf’s broader retail footprint (which matters when the punter is buying the voucher tonight for a session started tonight) is usually the tiebreaker.
Pay-by-Phone — Why It Doesn’t Exist in Australia
“Pay by phone casino” is the search phrase that catches every AU punter who has heard about direct carrier billing in the UK — where a casino deposit can be charged straight to a Telstra, Optus, or Vodafone monthly bill through Boku, Siru Mobile, or Payforit — and assumes the same rail exists here. It does not. No offshore casino accepting Australian players supports true carrier billing for AU accounts in 2026. Australian carriers do not process gambling merchant category codes through their billing systems the way UK carriers do, and no offshore operator has built the integration on the merchant side because the traffic does not exist.
What the search phrase usually reflects is a want for mobile-friendly deposit — a rail the punter can complete on their phone in the same session they open the casino. Australia has that in abundance, just not under the “pay by phone” label. PayID moves money in under sixty seconds from any AU banking app. Apple Pay and Google Pay wrap the underlying card into a biometric-authenticated tap. E-wallets like Skrill and Neteller run on a mobile browser or a wallet app. Crypto exchanges push funds from a mobile trading app in the same window a Solana deposit takes to confirm on-chain. Any of these solve the mobile-friendly problem. None of them are carrier billing. The reader arriving at an “AU pay-by-phone casino” search deserves the flat answer that the rail does not exist here, and the redirect to the alternatives that actually do.
Cryptocurrency — The Fastest Cashout Rail on the Menu
Crypto is the rail that inverts the deposit/withdrawal asymmetry that defines every other family on this list. Deposits on chains like Bitcoin or Ethereum take 5–30 minutes to confirm to the operator’s threshold, so the deposit side is slower than PayID; withdrawals, on the other hand, arrive at the reader’s wallet within an hour of operator approval on almost every chain, and the operator’s pending window is usually shorter for crypto than for fiat (many AU-facing operators run crypto withdrawals through a lighter approval queue because the transaction is push-only and irreversible). The result is the fastest cashout rail available, sitting well ahead of e-wallets and hours ahead of card refunds.
The other quirk of crypto is that it operates entirely off the AU banking rail. A punter who deposits Bitcoin sourced from an AUSTRAC-registered exchange (CoinSpot, Swyftx, Independent Reserve, Kraken AU) does so through an exchange account funded with PayID from the punter’s bank — but the exchange-to-casino leg happens on chain, outside anything the January 2027 bank-blocking framework can touch directly. The banking system sees “PayID transfer to CoinSpot” rather than “PayID transfer to Offshore Casino Ltd.” The regulator’s line of sight is one hop shorter, which is a structural reason the crypto rail is likely to grow as the 2027 date approaches.
The table below breaks down the crypto family on the axes that actually matter for casino play: typical network fee, confirmation time, and the network choice for USDT. Every coin below is universally supported at AU-facing crypto casinos; the differences among them are speed, cost, and how many things can go wrong when the reader sends.
| Coin | Typical network fee | Confirmation time | Best-supported network | Notes |
|---|---|---|---|---|
| Bitcoin (BTC) | A$2–A$8 | 10–30 min | Native L1 | Reference rail, highest fees |
| Ethereum (ETH) | A$2–A$20 (gas variable) | 3–10 min | Native L1 | Second-widest acceptance, ERC-20 host for USDT |
| Tether (USDT) | ~A$1 on TRC-20 | 3–15 min | TRC-20 (Tron) | Wrong-network send is irreversible |
| Litecoin (LTC) | Under A$0.05 | 5–10 min | Native L1 | 2.5-min blocks, cheap and fast |
| Bitcoin Cash (BCH) | Under A$0.05 | 10–20 min | Native L1 | BTC fork, lower fees, narrower acceptance |
| Solana (SOL) | Fractions of a cent | Under 1 min | Native L1 | Fastest-growing rail |
| Dogecoin (DOGE) | Under A$0.05 | 10–30 min | Native L1 | Enables sub-A$5 minimums |
Which cryptocurrency has the lowest fees for casino deposits and withdrawals in Australia?
Solana at fractions of a cent, then Litecoin, Bitcoin Cash and Dogecoin under five cents. USDT on TRC-20 sits near a dollar. Bitcoin runs A$2–A$8, Ethereum gas A$2–A$20 by congestion. For small frequent deposits, Solana or Litecoin wins; for one large deposit the gap barely matters.
Bitcoin (BTC)
Bitcoin is the reference crypto rail at AU-facing offshore casinos. Universal acceptance, best-understood mechanics, deepest wallet ecosystem, highest per-transaction fees of the family. A BTC deposit typically clears after one to three confirmations on the operator’s side, which takes 10 to 30 minutes; withdrawal to a punter’s wallet arrives in under an hour of operator approval. Network fees sit between A$2 and A$8 for a standard transaction, higher during congestion peaks, and the operator absorbs no part of that — the fee comes out of the punter’s transfer amount or is paid on top depending on the exchange or wallet software the punter uses.
The reader picks BTC when acceptance is the priority. Every AU-facing crypto casino accepts Bitcoin; some do not accept Solana or Bitcoin Cash. For a single large deposit where the network fee is a small percentage of the amount moved, BTC’s mechanics are straightforward and its history in the market is long. For high-frequency small deposits, the per-transaction fee compounds, and readers who move money in smaller amounts multiple times per session usually shift to Litecoin, Solana, or USDT on TRC-20 to avoid the fee stack.
Ethereum (ETH)
Ethereum sits second in AU-facing crypto casino acceptance and first in versatility because it hosts USDT and a range of other ERC-20 tokens. A deposit takes 3 to 10 minutes to reach the operator’s confirmation threshold, and withdrawals to a punter’s wallet arrive in under an hour of operator approval. Gas fees are the wildcard — ETH network activity determines the transaction cost in real time, and the range spans A$2 during quiet windows to A$20 or more during congestion peaks. The exchange or wallet software the reader uses picks a gas price; readers who want to keep costs down can set custom gas priorities in wallets like MetaMask or use a scheduling feature on some exchanges.
The reason to pick ETH over BTC at any given operator sits in fee efficiency for larger transactions and access to ERC-20 USDT if the operator prefers ERC-20 over TRC-20. For USDT specifically, ETH is usually the more expensive host chain (ERC-20 gas is higher than TRC-20 fees by a wide margin), so unless the operator only supports ERC-20, the reader should pick TRC-20 for USDT and use ETH for actual ETH transactions.
Tether (USDT)
USDT is the stablecoin most AU-facing crypto casinos accept, and its economics differ from every other crypto rail because the coin’s value is pegged to the US dollar. The casino balance denominated in USDT does not swing with market volatility between the deposit and the cashout — a punter who deposits 100 USDT and withdraws 150 USDT after a winning session takes home the AUD equivalent of 150 USD at that day’s exchange rate, without the “did the coin move against me?” risk that BTC or SOL carry. That stability is the reason USDT has grown to dominate settlement at crypto casinos.
The network choice is where the reader can lose the deposit entirely. USDT exists on multiple chains (ERC-20 on Ethereum, TRC-20 on Tron, SPL on Solana, BEP-20 on BNB Chain), and sending USDT to the wrong network at the operator’s cashier is irreversible — the funds go to an address on a chain the operator does not monitor, and there is no support ticket that recovers them. TRC-20 is the practical fastest and cheapest network at around A$1 per transaction and 3-to-15-minute confirmations; ERC-20 inherits Ethereum gas costs; SPL on Solana carries fractions of a cent in fees and sub-minute confirmations. Before any USDT deposit, the reader must check the operator’s cashier for the exact network name and match it to the sending exchange or wallet’s network dropdown. That single step avoids the single most expensive user mistake in the crypto family.
Litecoin (LTC)
Litecoin sits third in AU-facing crypto casino acceptance behind Bitcoin and Ethereum, and first in the “cheap and fast without wild fee swings” category. Launched in October 2011 as a Bitcoin fork optimised for payments, LTC uses a 2.5-minute block time (a quarter of Bitcoin’s 10 minutes) and settles transactions at fees consistently under five cents. Deposits clear in under eight minutes at most operators, and withdrawals to a punter’s wallet arrive in under an hour of operator approval.
For readers who move money in smaller amounts frequently, LTC is the practical choice. The cost per transaction is negligible enough that ten deposits stacked across a session cost less than a single BTC transaction, and the confirmation-time reduction over BTC makes the deposit-side wait tolerable in a way BTC’s 10-to-30-minute range often isn’t. Acceptance among AU-facing crypto casinos is broad enough that the reader rarely picks between LTC and no-LTC — most operators that carry BTC also carry LTC. The tradeoff, if there is one, is ecosystem depth: LTC’s wallet ecosystem and exchange support is narrower than BTC or ETH, so the reader picking LTC as their primary rail should confirm their exchange (CoinSpot, Swyftx, Independent Reserve, Kraken AU all support LTC) and their wallet (Trust Wallet, Exodus, Coinbase Wallet all support LTC) handle it before committing.
Bitcoin Cash (BCH)
Bitcoin Cash is the August 2017 Bitcoin fork that raised the block size to reduce fees and increase transaction throughput. On the fee side, BCH sits with LTC at under five cents per transaction; on the confirmation side, BCH uses BTC’s 10-minute block time, so deposits take 10 to 20 minutes to clear at most operators. Withdrawals to a punter’s wallet arrive in under an hour of operator approval, matching the crypto family standard.
Acceptance at AU-facing casinos is narrower than BTC, ETH, LTC, or USDT — BCH sits mid-pack in the crypto family for casino availability, ahead of some altcoins but behind the top four. For a reader who happens to hold BCH from an earlier Bitcoin fork claim or from a specific exchange balance, using it at a supporting operator is a working option with the same round-trip economics as LTC. For a reader choosing a crypto rail from scratch, LTC’s slightly wider acceptance and identical fee profile make it the more sensible pick over BCH in most cases.
Solana (SOL)
Solana is the fastest crypto rail on the AU-facing casino menu in 2026 and the fastest-growing in acceptance count. Mainnet launched in March 2020, and the chain’s design (parallel transaction processing, a Proof of History timing mechanism, single-slot finality) delivers sub-second confirmations at fees measured in fractions of a cent. A deposit clears almost immediately after the operator’s confirmation threshold; withdrawals arrive at the reader’s wallet inside an hour of operator approval, and the network side of the round trip is essentially free.
The rail’s real edge sits in what it enables. Solana-native casino stacks — where the game outcome logic itself runs on-chain rather than in the operator’s back office — are a small but growing category, and they leverage SOL’s throughput and cost profile to run games at a per-spin cost the fiat rails cannot match. For the reader who wants the fastest, cheapest deposit and cashout combination and does not need the deepest ecosystem, Solana is the choice. Acceptance count is behind BTC and USDT but expanding fast: every major AU-facing crypto operator either supports SOL now or has it on the roadmap for the current or next cashier update. The one caveat is the same USDT wrong-network warning in reverse — sending SOL to a non-Solana address is irreversible, so the network dropdown check at the sending exchange or wallet remains mandatory.
Dogecoin (DOGE)
Dogecoin is the meme-origin altcoin that unexpectedly earned a place at casino cashiers by delivering fees under five cents and confirmation times inside 30 minutes. Acceptance is narrower than BTC / ETH / USDT / LTC — DOGE sits at a smaller set of AU-facing crypto casinos — but the coin’s structural advantage is genuine: it enables true sub-A$5 casino deposits that no fiat rail can match economically. The reference example lives in the source archive at 7Bit Casino, where the Dogecoin minimum sits at A$1.20, the lowest documented deposit floor in the AU-facing offshore market.
For readers exploring low-stakes play — a A$5 or A$10 session where the deposit fee on a card or a wallet would eat a meaningful percentage of the balance — DOGE is a working option provided the operator supports it. For everyone else, DOGE sits behind LTC and SOL for general-purpose deposits: LTC has broader acceptance and identical fee economics, SOL has faster confirmations and even lower fees. DOGE’s niche is the low-floor session, and within that niche it works as advertised.
Deposit Floors and Welcome-Bonus Interaction
Every rail on the menu carries a real deposit floor that differs from the marketing claim on the operator’s landing page. The “A$1 minimum” and “A$5 minimum” headlines that anchor a significant chunk of AU-facing affiliate content usually refer to a specific outlier route — Dogecoin at A$1.20, a promotional first-deposit tier that expires in 24 hours, or a payment method the punter is not actually going to use — while the everyday floors for the rails most punters pick sit higher. Setting expectations honestly matters because a A$1 deposit that lands in a balance with a A$50 withdrawal minimum is a A$49 problem waiting to happen.
The real minimums by rail land roughly as follows. NPP rails (PayID, Osko, instant bank transfer) sit at A$10 at most operators, with a handful lifting to A$20 to align with their withdrawal floor. BPAY sits at A$20 or higher because settlement takes days and operators do not want small-balance deposits pending overnight. Card rails run A$20 at most cashiers, with some pushing to A$30 to cover processor economics. E-wallets sit at A$10 to A$30 depending on the wallet and operator combination — Skrill and Neteller at A$10, MiFinity at A$15, PayPal often at A$10 where accepted. Vouchers sit at A$10 to A$20, matching the physical denomination minimums. Crypto floors vary by coin: BTC / ETH / USDT typically A$20 equivalent, LTC and SOL similar, DOGE at the operator’s discretion down to A$1.20 in the reference case.
Welcome-bonus interaction is the second thing to know before picking a first deposit rail. Most AU-facing operators exclude specific payment rails from bonus eligibility — the exclusion list usually names Skrill, Neteller, and ecoPayz / Payz, occasionally MiFinity, and occasionally card deposits under a specific threshold. Depositing on an excluded rail either forfeits the welcome bonus entirely or triggers a bonus that carries higher wagering multipliers. The reader chasing a first-deposit welcome package needs to read the specific operator’s bonus terms before picking a rail; PayID, crypto, and Neosurf are typically bonus-eligible at most operators, but each cashier’s rules are the source of truth.
What is the real minimum deposit per rail at AU-facing offshore casinos?
Roughly A$10 on PayID, Osko and instant bank transfer; A$20 on BPAY, cards and most vouchers; A$10–A$30 on e-wallets; A$20 equivalent on BTC, ETH, USDT, LTC and SOL; as low as A$1.20 on Dogecoin where supported. “A$1 minimum” fiat marketing is almost always an outlier route.
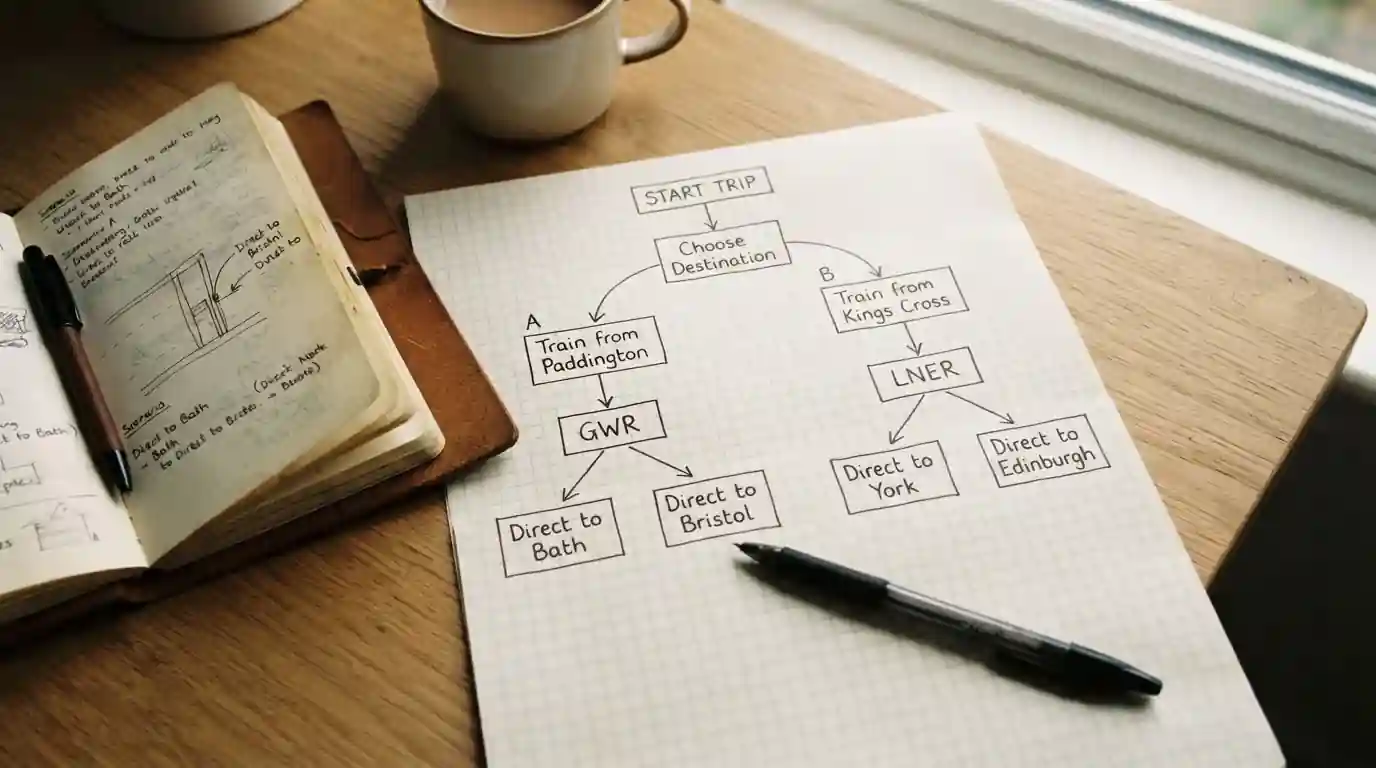
How to Pick a Rail for Your Scenario
The point of the map above is to shorten the reader’s decision. Every rail has a clear best-use case, and matching the rail to the session is a five-minute question rather than a research project. Below, running through the scenarios that cover most AU-facing casino sessions.
For the fastest possible cashout, crypto wins outright. Solana at the top, Litecoin and Dogecoin close behind, USDT on TRC-20 for a stable-value cashout, Bitcoin and Ethereum where acceptance requires them. The operator’s pending window still sits upstream, but once the operator releases funds, the rail delivers to the reader’s wallet inside an hour on every mainstream chain. E-wallets (Skrill, Neteller) come next at 15 minutes to 24 hours. PayID and Osko land in the same tier when the operator supports two-way NPP, which not all do. Card refunds sit at the back at three to five business days, and BPAY / vouchers cannot cash out at all.
For no bank-statement trace, vouchers are the reference rail. Neosurf bought with cash at a servo or a newsagent, redeemed at the casino, leaves no card statement line and no bank-transfer memo. CashToCode and Paysafecard behave the same way. The AUSTRAC A$1,000/day cap sets the ceiling for how much can move this way. Crypto sits in second place on the privacy dimension: the exchange purchase leaves a “CoinSpot” or “Swyftx” line on the bank statement, but the exchange-to-casino step is on-chain and outside the banking system’s view.
For the cheapest daily top-up, PayID is free. Every AU debit card top-up to an e-wallet costs 2.5%. Every card deposit at a cashier may carry a cash-advance flag on credit. Crypto network fees range from fractions of a cent (Solana) to A$8 (Bitcoin in congestion), with LTC and USDT-TRC-20 in the middle. For a punter making frequent small deposits, PayID or LTC or SOL are the sensible picks; every other rail extracts a margin somewhere.
For the largest single deposit, PayID and crypto are the practical choices. PayID’s ceiling is set by the sender’s bank — most AU consumer accounts sit at A$1,000 to A$25,000 per day out of the box, and most banks lift the ceiling on request. Crypto has no per-transaction ceiling on the chain side; the operator’s cashier max applies instead, and most AU-facing crypto operators set no ceiling or a very high one. Vouchers are capped at A$1,000/day by AUSTRAC; e-wallets and cards run into wallet-side or issuer-side daily limits before the casino’s cashier does.
For thinnest KYC, PayID and PayPal have the KYC already done — the bank knows the reader, the wallet knows the reader, the casino inherits the identity confirmation implicitly. Crypto sits in second place: the exchange has run KYC, the casino often accepts crypto deposits without triggering its own KYC step until withdrawal time. Vouchers are the reader-side KYC minimum — the retailer does not ask for ID for a A$50 voucher — but the AUSTRAC cap and the operator’s cashout KYC catch up eventually. Cards and e-wallets sit in the middle; both carry KYC on the wallet or card side but re-KYC on the casino side at first cashout.
The last thing to line up before the first spin is the withdrawal path. A punter depositing on a deposit-only rail (BPAY, any voucher, most credit cards) needs a second rail configured before the winning session forces the question. Setting up a Skrill or Neteller wallet, or opening a CoinSpot account and buying a small amount of USDT to hold as the withdrawal-receiving wallet, takes fifteen minutes and prevents the “big win, no cashout path” scramble that has cost more than one AU punter their winnings when a KYC loop hit at the worst possible time. That single planning step turns the payments menu from a series of independent choices into a coherent map matched to the reader’s own session shape.
Casino Deposit Methods Australia 2026 — Full Comparison
Content created by the «Payment Methods Online» team